S
Sharon
Google reviewGreat guy! Nick was the most helpful in my first home buying experience. Very reliable and personable. Highly recommend.
Read Google reviews
Kanata · West Ottawa
A licensed mortgage agent for Kanata home buyers and homeowners across west Ottawa. Whether you are buying your first place in Bridlewood, renewing a mortgage in Kanata Lakes, or refinancing to free up cash, I help you find the right lender and the right structure.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316 · 14 years · serving Kanata and west Ottawa.
The short answer
Your mortgage agent for Kanata is Nick Bachusky, a licensed Mortgage Agent Level 1 with Referral Mortgages Inc., FSRA brokerage licence #13316, working under Referral Mortgages Inc. As a mortgage agent in Ottawa, I serve Kanata, west Ottawa, and the wider Ottawa area across Ontario only, not Quebec or Gatineau. I shop multiple lenders to match your purchase, renewal, or refinance, and reply to most messages within about 30 minutes.
Who it's for
Most people who call me from Bridlewood, Katimavik, or anywhere else in Kanata are not shopping for a mortgage in the abstract. They are at a specific moment in life, and I built my practice around the four that come up most.
Buying your first home. I walk you through pre-approval, down payment options, and the real numbers before you start touring. See first-time home buyer mortgages in Ottawa.
Renewing at the end of your term. The work is about testing whether staying put or switching lenders actually saves you money. See your mortgage renewal strategy.
Tapping equity with a refinance. For renovations, debt, or a second property, this path lays out the trade-offs, penalty included. See refinancing to free up equity.
Separating or divorcing. I treat this as a real specialisation, helping one partner buy out the other or restructure the home loan so both people can move forward. See divorce and separation mortgages.
It is the piece most agents skip, and it matters when you are in it. As the mortgage agent Kanata families come back to, I treat every file the same way, and every client gets the same promise: you should feel like my only client.
"Every client should feel like my only client." Nick Bachusky
On the ground here
The Kanata housing market is not one market, it is several. What you can buy, and how a lender reads your file, shifts a lot from one community to the next. I work across all of west Ottawa, so the starting point is always the neighbourhood you actually want.
Kanata Lakes, around $836k. The executive end of the map, golf-adjacent, with the highest values in the suburb.
Bridlewood, around $744k. The large 1990s and 2000s family suburb, and the one I get asked about most.
Beaverbrook, around $605k. The oldest planned community here. Mid-century houses on big lots under mature trees.
Katimavik, around $551k. Family friendly, built in the 1980s, good schools, and the most approachable prices of the four.
Morgan's Grant. Sits next to the tech hub, so it draws a lot of tech professionals who want a short commute.
Glen Cairn. The oldest part of South Kanata, and still among the more affordable pockets.
Those figures are a dated June 2026 local MLS snapshot, illustrative only, and they move month to month. They matter because they cross lender lines: under CMHC rules the minimum down payment is 5% up to $500k, then 5% on the first $500k plus 10% above it, and default insurance is required whenever you put down less than 20%. Homes at $1.5M and above cannot be insured at all, so 20% down is the floor. Part of my job is mapping your target price to the right tier before you fall in love with a listing. Put a Kanata price through the Ottawa mortgage payment calculator first and you will walk into showings knowing your real number.
The Kanata North tech economy genuinely changes how a mortgage gets approved. The tech park is Canada's largest, with more than 540 companies and roughly 33,000 employees, and much of that workforce lives close by. Many are paid partly in RSUs, bonuses, and variable income, which banks tend to handle awkwardly. Lenders usually want about a two year history before they will count it, and how it gets averaged is a lender and insurer policy call. Documented well, that income adds real borrowing power. I package the history so it actually counts.
New builds are the other Kanata reality. Active subdivisions sell on staggered deposits and long closing timelines, which is a different animal from a resale purchase. Financing has to line up with the builder's schedule, rate holds need to stretch further, and pre-approval often has to be re-confirmed closer to completion. New freehold builds also carry Tarion protection, and buyers in the current eligibility window may qualify for the enhanced GST rebate on eligible homes, both worth confirming with a tax professional. If you are weighing a new build, my purchase and pre-approval page walks through the timing, and a condo mortgage has its own lender rules again.
One boundary to be clear about: I am licensed in Ontario and arrange every mortgage on the Ontario side, serving Kanata and the broader Ottawa-Carleton area. I do not arrange mortgages across the river in Quebec.
Every client should feel like my only client.
What I arrange
Whatever stage you are at, from a first pre-approval to a renewal you want to shop properly, there is a service built for it. Each one is handled by me directly, for Kanata buyers and owners.
See where rates sit today and what actually applies to your situation, not a headline number. I line up options from many lenders so you compare the real cost.
today's Ottawa mortgage ratesGet a solid pre-approval before you shop Kanata listings, so you know your budget and can make a confident offer.
getting pre-approved for a purchaseNew to owning? I walk you through down payment, the rebates you qualify for, and every step to your first Kanata home.
first-time home buyer mortgages in OttawaYour renewal letter is a starting point, not the best you can do. I check whether switching lenders saves you real money.
renewing a mortgage in OttawaPull equity to renovate, consolidate debt, or fund a goal. I show the numbers, including any penalty, before you decide.
refinancing to consolidate debt or free up equitySeparating and need to buy out, sell, or restructure the home? I handle the mortgage side with care and clear timelines.
mortgage help during separation or divorceBuying a Kanata condo or townhome comes with its own lender rules. I know which lenders approve which buildings.
condo mortgages in OttawaAgent vs bank
A bank can only offer you what sits on its own shelf. If your file is anything but simple, that shelf gets narrow fast. The most common thing I hear in Kanata is some version of "the bank had no clue how to deal with my income," usually from tech workers paid partly in RSUs, bonuses, or variable pay.
I shop more than 30 lenders and work for you, the borrower, not for any one lender. I am a licensed Mortgage Agent working under Referral Mortgages Inc., which is the Kanata mortgage broker relationship most people picture.
Being squeezed into your bank's single product when a different lender fits your income far better.
Missing a lower rate because you never saw what the wider market offered. When a friend "got a better rate," it is almost always because they compared lenders.
A renewal or switch handled as an afterthought. Since late 2024, many straight lender switches at renewal no longer require you to requalify under the stress test, which can open up better options that a bank has no reason to mention.
Looking only at the rate and ignoring the total cost. The penalty terms, prepayment rules, and fine print can cost far more than a small rate difference over the life of the loan.
Getting handed off between departments, so no one person actually knows your file.
Your account being there is not a reason to stay. Plenty of people start out looking for a mortgage broker Kanata side and end up with a mortgage agent Ottawa homeowners can call direct. Same job, and it is the licence I actually hold. The real question is which lender gives you the better overall deal.
Want the process end to end? Read how it works. Renewal coming up? Start with planning your mortgage renewal.
"A rate is not just a rate, the penalty matters." Nick Bachusky
A mortgage has a lot of moving parts. That is the part I handle for you, so you can focus on the home.
Why trust Nick
Your mortgage is one of the biggest financial commitments you will ever make, so it matters who is on the other side of the file. In Kanata, that person is me. I work for you rather than for a single lender, which means I shop your situation across many banks and lenders instead of one rate sheet.
14 years
in mortgages
Including years on the big bank side at RBC and TD before I moved to the broker channel. I know where files slow down from the inside.
FSRA brokerage licence #13316
licensed in Ontario
Mortgage Agent Level 1 with Referral Mortgages Inc. Every Kanata file is arranged on the Ontario side.
Only me
on your file
From the first conversation to the day your mortgage closes. No assistant, no call centre, no handoff partway through.
~30 min
typical reply time
During the day, whether you message, call, or email. You are one message away from a straight answer.
You can read more about my background and approach on the about page, or start straight from the home page if you want the full picture first.
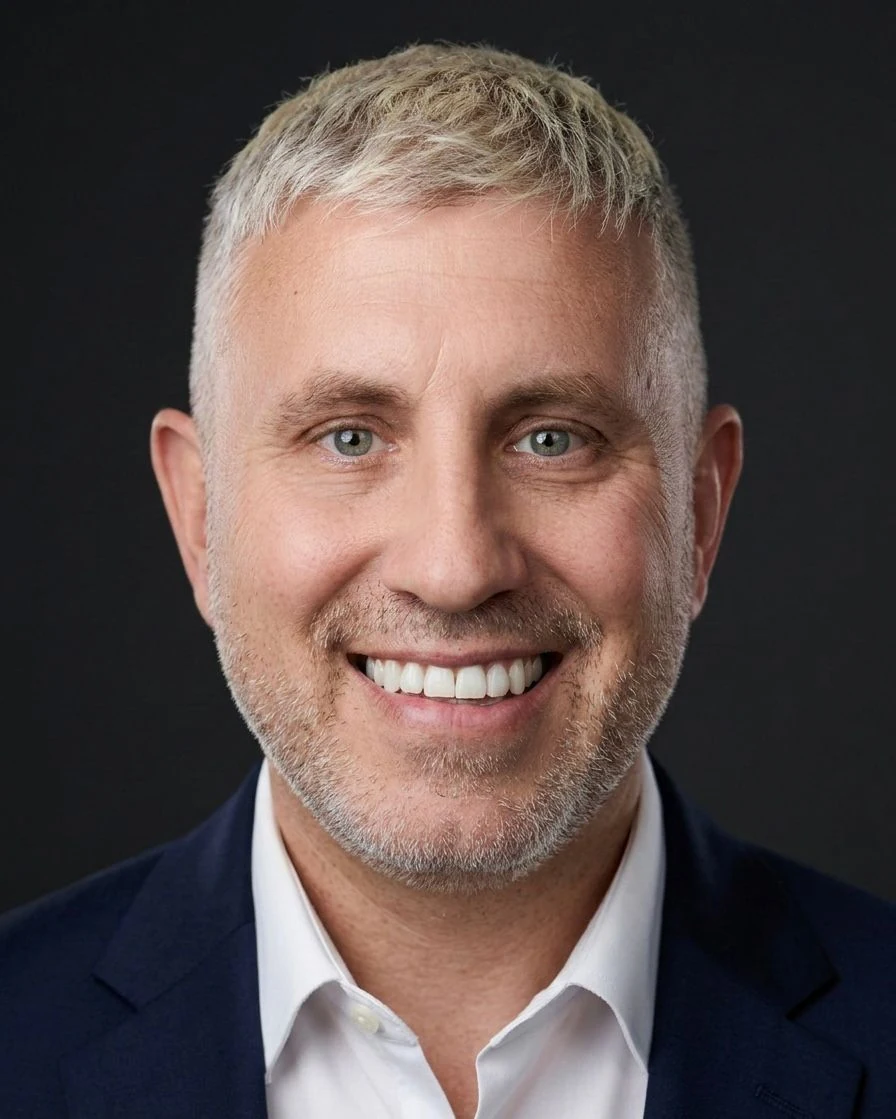
Nick Bachusky, Mortgage Agent Level 1, Referral Mortgages Inc., FSRA brokerage licence #13316.
4.9 stars from 64 Google reviews left by clients I have worked with across Ottawa.
Get in touch
Getting a mortgage does not need to be stressful. Leave your details and I reply within about 30 minutes during business hours.
Kanata mortgage FAQ
No. For a standard residential mortgage you do not pay a fee for my service, and any rare exception on a private or complex file is put in writing before you commit.
Your bank can only offer its own products, and it has little reason to lead with its sharpest rate for a client it already has. A mortgage agent shops one application across 30 or more lenders and works for you, not for a single lender. To be clear, I am a licensed Mortgage Agent working under Referral Mortgages Inc. I compare the whole deal, not just the headline number, because a rate is not just a rate, the penalty matters.
Down payment tiers in Ontario, as of June 2026, work like this: Up to $500,000, minimum 5 percent. $500,000 to $1.5 million, 5 percent on the first $500,000, plus 10 percent on the portion above. Over $1.5 million, minimum 20 percent, because default insurance is not available at that price. Under 20 percent down, default insurance (CMHC, Sagen, or Canada Guaranty) is required. With Kanata prices spread from roughly $551,000 in Katimavik to about $836,000 in Kanata Lakes, the tier that applies to you depends on the exact home, so it is worth mapping before you shop.
The stress test means you must qualify at the higher of your contract rate plus 2 percent, or 5.25 percent, whichever is greater. This benchmark, set by OSFI and effective June 2021, is why online affordability calculators often overstate what a lender will actually approve. I run your real numbers against the qualifying rate up front, so what you think you can afford and what a lender approves are the same figure before you make an offer. You can sketch a first estimate on the mortgage calculator page.
As of November 2024, OSFI no longer expects lenders to re-apply the stress test when you switch an uninsured mortgage between federally regulated lenders at renewal. That change was made to give renewing borrowers more room to shop. You still need the new lender to approve the file and a lawyer or notary to register the switch, but you are no longer trapped by the qualifying rate simply because you want a better deal. I can review your renewal letter and tell you whether shopping is worth it.
Many Kanata North tech earners hit the same wall: a bank pre-approval where the person has little idea how to handle variable income. Lenders typically want roughly a two-year history of receiving that income before they will count it, and the averaging method is set by each lender’s policy, so it is document-heavy. Done well, counting around $10,000 a year of extra before-tax income can add roughly $40,000 to $50,000 of borrowing power. These are illustrative figures for June 2026, not a promise, and I will show you how to document it properly.
Start with a pre-approval so you know your real borrowing power before you house-hunt. From there I walk you through the pieces first-timers ask about most: the FHSA (up to $8,000 a year, $40,000 total in tax-deductible room), the RRSP Home Buyers’ Plan (up to $60,000 per person, funds in the account at least 90 days), and closing costs that usually add 1.5 to 3 percent on top of the down payment. Full detail lives on the first-time home buyer in Ottawa page.
A pre-approval usually holds your amount and rate for 90 to 120 days, and a resale purchase generally closes inside that window. New builds in Kanata run differently: staggered deposits, a long construction timeline, Tarion warranty coverage, and financing that has to be coordinated with the builder’s schedule and re-confirmed near completion. That is why I aim to have the mortgage complete about three weeks before closing, so you are focused on the house, not the financing.
Serving another part of Ottawa
I work with buyers and homeowners right across the city, not only in Kanata. If you are looking in another neighbourhood, start with the local page closest to you.
Get started
One clear next step, whenever you are ready. Start your application, or book a meeting at a time that suits you. No pressure, and every client should feel like my only client.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316. Rate, penalty and rule figures are dated examples for 2026, grounded in CMHC, OSFI, FCAC and Canada.ca, and are not guarantees.