S
Sharon
Google reviewGreat guy! Nick was the most helpful in my first home buying experience. Very reliable and personable. Highly recommend.
Read Google reviews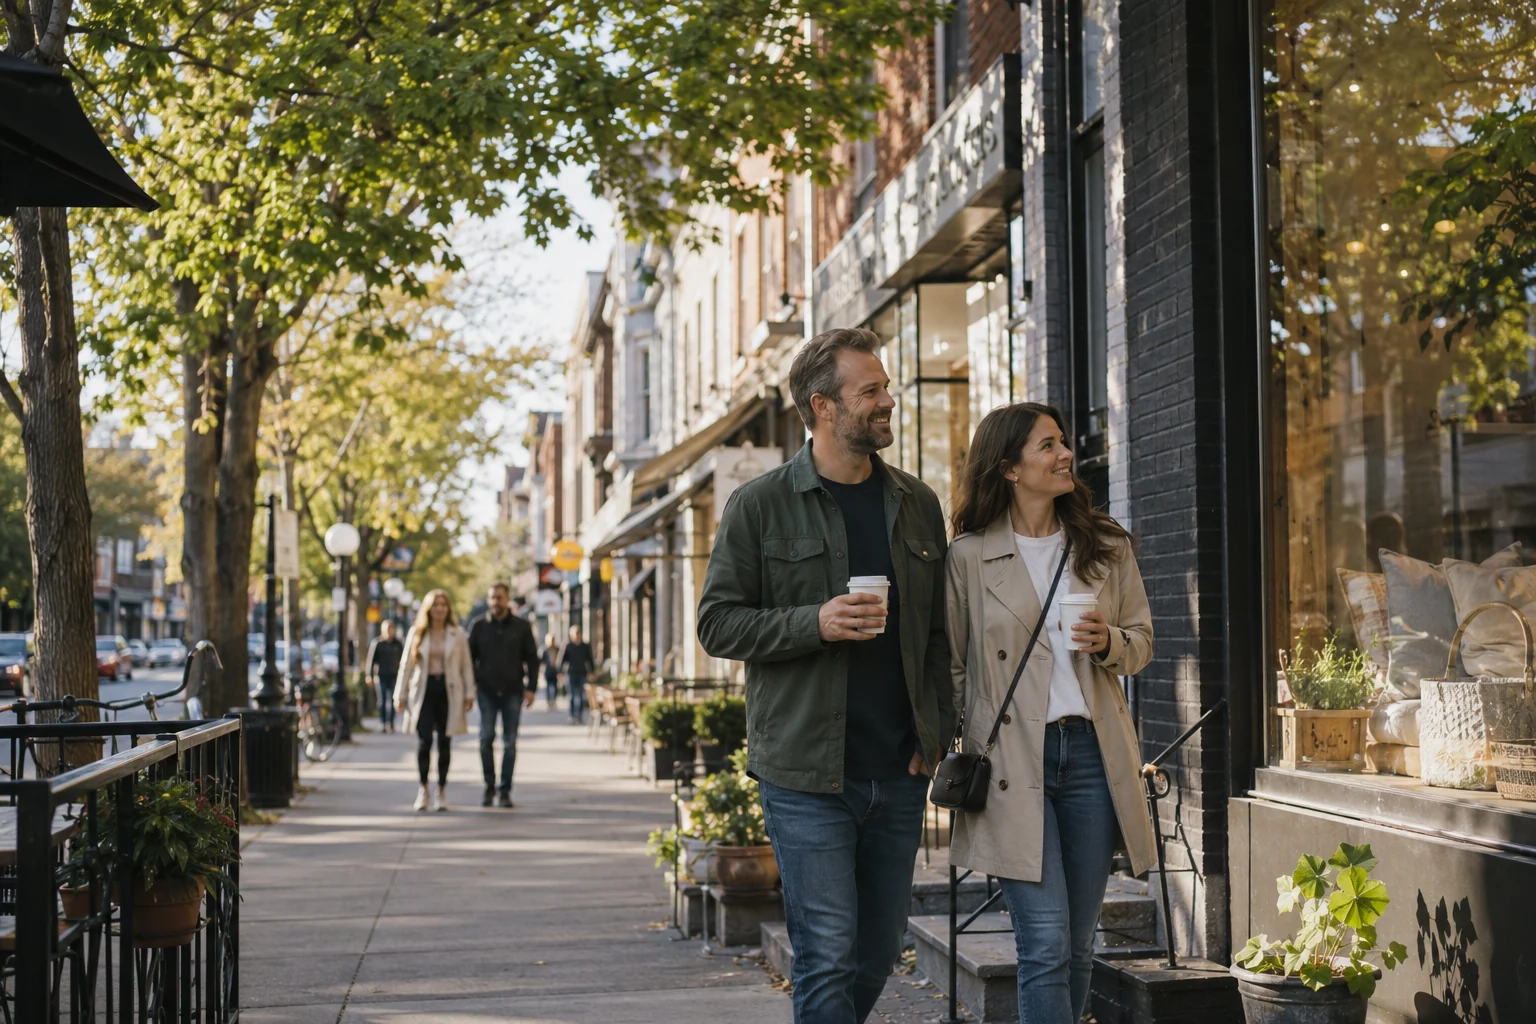
The Glebe · Central Ottawa
Financing a home in the Glebe, from a Bank Street century brick to a Lansdowne condo, with a licensed local agent who answers fast. I arrange purchases, renewals, and refinances across the Glebe and central Ottawa.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316 · serving the Glebe and central Ottawa.
The short answer
A mortgage agent The Glebe buyers can reach directly is me, Nick Bachusky. I arrange purchases, renewals, and refinances for homes from the Bank Street corridor to Lansdowne. I am a Mortgage Agent Level 1 with Referral Mortgages Inc., FSRA brokerage licence #13316 with Referral Mortgages Inc., serving central Ottawa. I shop many lenders to fit your file, then handle the paperwork through closing.
Why an agent
A mortgage agent takes your situation to many lenders at once, then brings back the option that costs the least over the whole term. You fill in one application; I handle the documents and the lender questions. I work as a solo, independent mortgage agent in Ottawa, so your file is not handed to a junior or left in a queue. You deal with the same person from the first message to closing day, and I reply fast, often within about half an hour. As I put it, I am one WhatsApp message away.
Being local matters more in the Glebe than people expect. The housing stock here is old, mostly century Victorian and Edwardian brick, and lenders ask real questions about older homes. A local mortgage agent who works central Ottawa every week knows how those files read and which lenders are comfortable with them. You can call ten lenders yourself, but the catch is access: an agent reaches banks, credit unions, and monoline lenders on one application, including ones that do not deal with the public. Everything runs by phone, screen-share, and WhatsApp, so you get that local knowledge without booking time off. Whether an agent or your bank is the better route is a fair question, and a later section answers it straight.
"Every client should feel like my only client." Nick Bachusky
On the ground here
The Glebe sits about two to three kilometres south of downtown Ottawa, and Bank Street runs right through the middle of it. That corridor is the heartbeat of the neighbourhood, lined with independent shops, cafes, and more than sixty restaurants. To the east and south the Rideau Canal wraps the area, with Dow's Lake at the northwest edge and the world's largest skating rink in winter. It is a neighbourhood people buy into and stay in for decades.
The Glebe is compact and clearly bounded, hemmed by the Queensway, the canal, and Bronson Avenue. Those tight borders mean homes rarely come up and the ones that do move fast, so you want financing already sorted before a listing appears. The housing stock is part of the appeal and part of the puzzle: century Victorian and Edwardian brick east and west of Bank Street, Arts and Crafts four-squares from the 1920s, and Noffke-designed homes near Central Park. Real character, and also older wiring, older plumbing, and lenders who ask about it.
We serve the whole area a Glebe buyer thinks of as home, including the Glebe Annex west of Bronson, Dow's Lake, and Old Ottawa South across the canal near Carleton University. Newer Lansdowne Park condos at TD Place are part of the picture too. I am licensed in Ontario, so I cover Ottawa and area, not Quebec or Gatineau. You can reach Nick Bachusky by phone or WhatsApp at 613-294-4475, or apply online, from anywhere in the Glebe. The office is close by at 1320 Carling Avenue, Suite 205, just north of the neighbourhood.
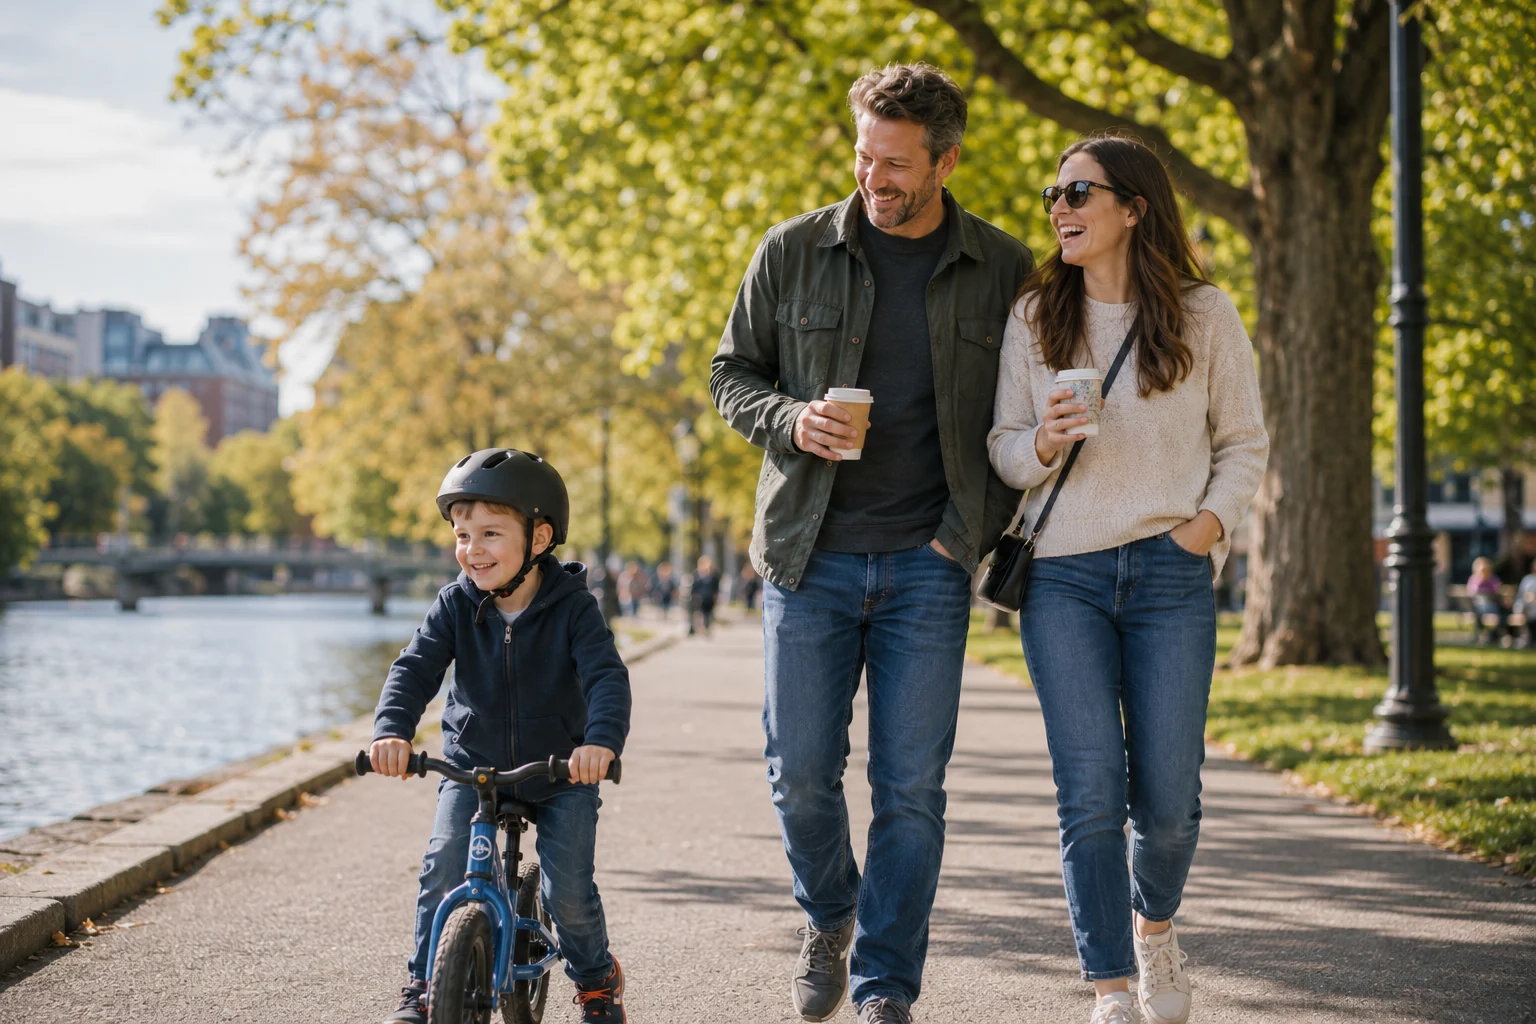
A neighbourhood people buy into and stay in for decades.
Agent vs bank
This is the honest question most Glebe buyers ask, so here is a straight answer. Your bank shows you one shelf, its own products. A mortgage agent compares many lenders and brings you the option that fits your file. I am a licensed Mortgage Agent working under Referral Mortgages Inc. I shop a wide range of institutional lenders, from the big banks to credit unions and monoline lenders with no branch you can walk into. As a dated 2025 to 2026 snapshot, my funded files spread across roughly a dozen lenders, so I can line up several offers side by side.
This is the objection I hear most. People say a bank once beat their broker's rate, so why bother. Fair, and I welcome the comparison. Go get your bank's number and bring it to me. If your bank truly has the better deal on total cost, I will tell you so, plainly. I have no reason to steer you into something worse, because I do not earn more by doing that.
Here is the part people learn the hard way. A rate is not just a rate, the penalty matters. Two mortgages can show the same number on the front page and cost you thousands of dollars apart if you break or move early. That is where a low headline rate can quietly become an expensive one. So the choice is less about who finds a cheaper number today, and more about who reads the whole contract with you and thinks past this term. Want the longer version? Read our guide on how Ottawa mortgage rates and penalties work, then message me with your file.
"A rate is not just a rate, the penalty matters." Nick Bachusky
Financing a Glebe home
The Glebe is century brick, high price tags, and a growing wall of condos near Lansdowne Park. Each raises a different financing question, and I handle all three by shopping multiple institutional lenders to fit the property in front of you.
Much of the Glebe is Victorian and Edwardian brick built before 1920. These homes come with quirks a lender cares about: knob-and-tube wiring, a 60-amp panel, galvanized or lead supply pipes, or a buried oil tank. Standard underwriters often will not fund a home with these systems until they are upgraded. There is a clean path for this. If a Glebe home needs updates, I can look at Purchase Plus Improvements, an insured, institutional product that bundles the purchase price and planned renovation cost into one insured mortgage, appraised on the finished "as-improved" value. CMHC can insure up to 95 percent of that value on an owner-occupied home of one or two units.
What I do here is match the file to the right lender. Some institutions are comfortable with the Glebe's older homes and their appraisal questions, and I shop the ones that are. If a specific home is too far gone, I will tell you plainly. Some of those situations fall outside what a Mortgage Agent Level 1 can arrange, and it is better to know that early.
The average Glebe home now sits well past a million dollars, so the down payment rules matter more here than in most of Ottawa. As of 2026, Canada raised the insured-mortgage price cap to 1.5 million dollars, effective December 15, 2024, a real change from the old one million dollar cutoff.
As a dated 2026 example, a home priced under 1.5 million can qualify for a high-ratio mortgage, meaning less than 20 percent down. The minimum is tiered: 5 percent on the first 500,000 dollars, then 10 percent on the portion above that up to the cap. A home at 1.5 million or more is not eligible for default insurance, so it needs a flat 20 percent down. Those tiers move the monthly payment a long way, so it is worth running a Glebe price through the Ottawa mortgage payment calculator before you set a budget. For these larger files, I shop multiple institutional lenders and compare them on total cost, not just the headline rate.
Southeast of the Glebe, Lansdowne Park is adding new residential towers, and condos are the entry point for many buyers. New-build and pre-construction closings work on a longer timeline than a resale purchase. For a Lansdowne condo, the offering is a long rate-hold pre-approval that carries you toward a closing date months away, plus the condo due-diligence knowledge to read a status certificate and reserve fund. I keep the mortgage side lined up while you focus on the unit. You can dig into the details on the Ottawa condo mortgage page.
A century home leans on Purchase Plus Improvements and lender appetite, a high-value home on the 1.5 million dollar cap and the tiered down payment, and a Lansdowne condo on a long rate-hold. If you want to renovate rather than buy, there is a refinance route on the Ottawa mortgage refinance page. The starting point for a purchase is the Ottawa purchase mortgage page, or a free chat with Nick about your specific address. Message me on WhatsApp at 613-294-4475.
A home you got with the right lender, and a plan that thinks past this term.
What I arrange
Buying, renewing, or refinancing in the Glebe? I help with the exact mortgage that fits your situation. Here is where to go next, each built around a real Ottawa need.
For a current, dated look at where rates sit and what shapes yours in the Glebe.
Ottawa mortgage ratesKnow your number before you tour homes along Bank Street, so you can make a confident offer.
purchase and pre-approval mortgages in OttawaFor buyers getting into their first place in central Ottawa, from down payment to every step.
first-time home buyer help in the GlebeWhen your term is ending and the first offer from your bank looks high, I check the real cost.
mortgage renewal strategy in OttawaPull equity for renovations on an older Glebe home, debt, or a lower rate. I show the numbers first.
mortgage refinancing in OttawaKeep or buy out a Glebe home during a separation, handled with care and clear timelines.
divorce and separation mortgages in OttawaFor buyers looking at Lansdowne and the Glebe’s condo stock, where each building brings its own rules.
condo mortgages in OttawaWhy trust Nick
I keep my practice deliberately small, on purpose. That is the level of care Glebe buyers say they want: someone responsive, patient with first-time questions, and willing to explain every step and every risk in plain words. As I put it, every client should feel like my only client.
14 years
in mortgages
Including time inside the big banks at RBC and TD, so I know how they price a file from the inside. I now work for you, not for one lender.
FSRA brokerage licence #13316
licensed in Ontario
Mortgage Agent Level 1 with Referral Mortgages Inc. I cover Ottawa and area, not Quebec or Gatineau.
~30 min
typical reply time
I answer my own phone and read my own messages. No call centre, no handoff. A question on a Saturday still gets answered.
3 weeks
finished before closing
I aim to have your mortgage broker complete about three weeks out, so your final days are about the house and the move.
You can read more about my background on the about page, or see the full picture on the home page.
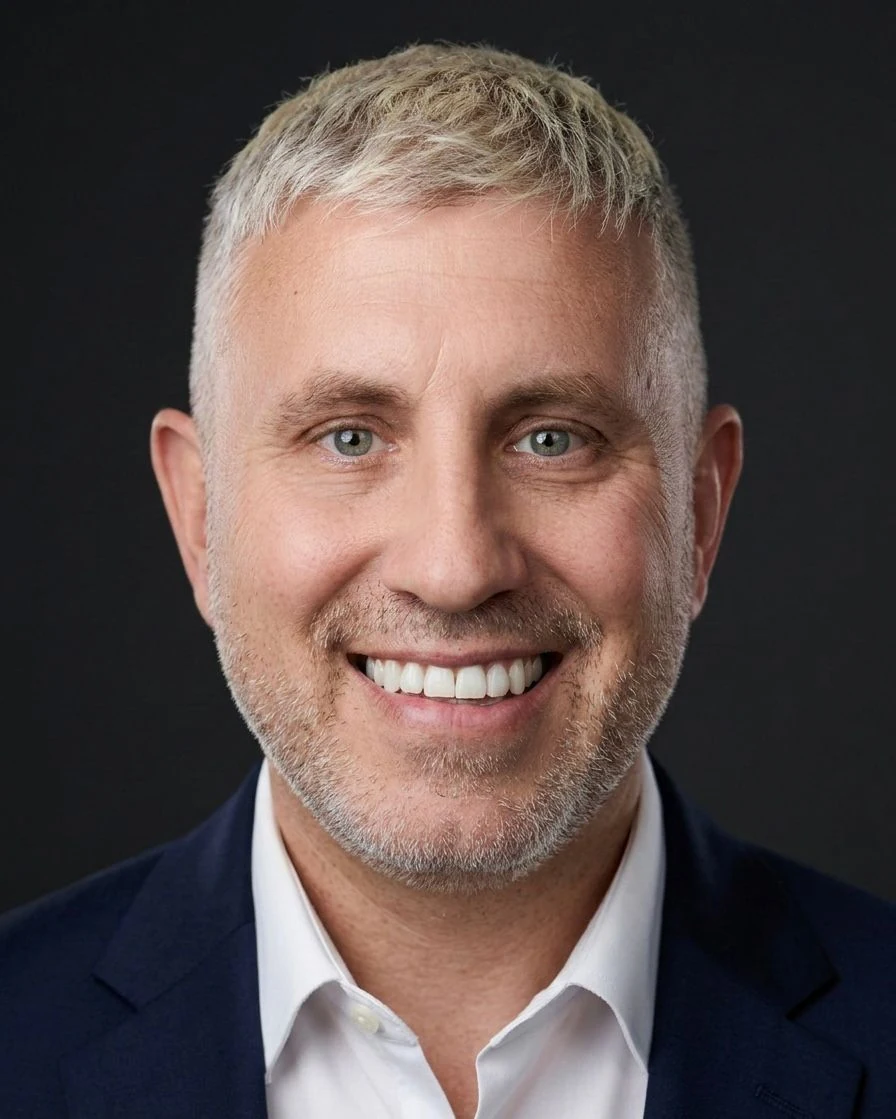
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316.
4.9 stars from 64 Google reviews left by clients I have worked with across Ottawa.
Get in touch
Getting a mortgage does not need to be stressful. Leave your details and I reply within about 30 minutes during business hours.
Glebe mortgage FAQ
For a standard residential mortgage you do not pay me a fee, and any rare exception is put in writing before you sign.
Both are licensed by the Financial Services Regulatory Authority of Ontario to arrange mortgages, so both can shop lenders for you. The difference is the licence tier. A mortgage broker holds a higher-tier FSRA licence and can supervise agents. I am a licensed Mortgage Agent working under Referral Mortgages Inc., FSRA brokerage licence #13316, which lets me arrange your mortgage with banks and National Housing Act approved lenders. For most Glebe buyers, the work you receive is the same.
Yes. The Glebe’s older brick homes can raise appraisal and lender-appetite questions, since things like knob-and-tube wiring, galvanized pipe, or an old oil tank make some lenders cautious. Where a home needs updates, the cost can often be rolled into an insured Purchase Plus Improvements mortgage against the improved value. I shop lenders comfortable with the Glebe’s older stock. Some homes that are too far gone fall outside what an insured file can cover, and I will tell you honestly if that is the case.
As of December 15, 2024, homes priced under $1.5 million can qualify for a high-ratio insured mortgage, so you may put down less than 20%. The tiered minimum is 5% on the first $500,000 plus 10% on the portion above that, per CMHC and Canada.ca. A $1.2 million home works out to $95,000 down. At $1.5 million or more, default insurance no longer applies and you need a flat 20%. This is a dated example, not a rate promise.
A pre-approval usually takes one to three business days. A full purchase file typically runs about 30 to 45 days from application to closing, covering document collection, the appraisal, and underwriting. My aim is to have your mortgage broker complete roughly three weeks before closing, so you are focused on the house, not the financing. I am one WhatsApp message away when a lender needs a document quickly.
Your bank shows you one shelf of rates: its own. A mortgage agent compares many lenders on total cost, not just the headline rate, because a rate is not just a rate, the penalty matters. If you break the mortgage early, a lender’s penalty can cost more than a small rate difference ever saved. I welcome you comparing your own bank at the same time, and I am never paid to steer you.
Serving another part of Ottawa
I work with buyers, renewers, and owners right across Ottawa, not just the Glebe. If you are looking at a home in another part of the city, or you know someone who is, start with the neighbourhood page closest to you.
Ready when you are
Apply online and I will review it personally, or book a time and I will call you. Either one gets you a straight read on your Glebe file.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316. Office: 1320 Carling Avenue, Suite 205, Ottawa, ON K1Z 7K8. Rate, penalty and rule figures are dated examples for 2026, grounded in CMHC, OSFI, FCAC and Canada.ca, and are not guarantees.