S
Sharon
Google reviewGreat guy! Nick was the most helpful in my first home buying experience. Very reliable and personable. Highly recommend.
Read Google reviews
Mortgage renewal · Ottawa
Your renewal letter is not a bill you have to pay as printed. It is the one moment you get real leverage on your rate. I am a licensed Mortgage Agent in Ottawa who reviews whether you should stay, switch, or renegotiate, then handles it.
The short answer
A mortgage renewal in Ottawa is when your current term ends and you sign a new one on the balance you still owe. You can renew with your existing lender or switch to another, and at the maturity date you can do either with no penalty. The catch is that the first rate your bank mails you is rarely its best. As a licensed Mortgage Agent under Referral Mortgages Inc., I review your stay-or-switch options.
Before your mortgage renews, compare your current lender's offer with the rates, penalties, and prepayment terms available elsewhere. I review the cost of staying or switching, explain any fees, and help you choose a term before your maturity date. Contact me while there is still time to compare offers and complete the paperwork.
If you are timing this renewal around interest rates, read my dated take on when mortgage rates will go down in Canada, framed around the Bank of Canada decision dates rather than a guess.
Your renewal letter is leverage, not a bill to sign as printed.
Why this renewal feels different
If you locked a mortgage in 2020 or 2021, you signed at rates the market has not seen since, and that term is now ending. The Bank of Canada estimates that about 60% of mortgage holders renewing in 2025 and 2026 will see their payment go up, and that five-year fixed borrowers renewing in 2026 face an average increase of roughly 20% over their late-2024 payment. That mortgage renewal payment increase is what keeps Ottawa homeowners up at night, and it is real, not hype.
In Ottawa the squeeze lands on a specific household. Roughly 22% of local jobs sit in public administration, the highest share in Canada, and the National Capital Region has shed about 8,000 public-service positions. The four-day return-to-office mandate adds commuting, parking, and childcare costs that can reach $6,000 to $7,000 a year for a suburban driver. Layer on the City of Ottawa's 3.75% property-tax increase for 2026 (about $166 more on an average urban bill) and a 4.5% water rate increase, and the room to absorb a worse renewal offer shrinks. This is why shopping the renewal matters more here than in a typical Ontario city.
A higher payment is not a verdict. There are honest moves at renewal that soften it, and we will walk through every one of them.
How it works
First, what is a mortgage renewal? Here is the mortgage renewal process in plain terms. Your mortgage has a term, often three or five years, and an amortization, the full number of years to pay it off. The term is what ends. When it does, the balance does not disappear, you simply sign a new term on what is left. People call that a mortgage term renewal, or just renewing your mortgage. By law your current lender must mail you a renewal statement at least 21 days before your term is up, showing the balance, the rate, the payment, and any fees. Most lenders send an offer earlier than that, valid for the 30 days before maturity.
The 120-day timeline
Four months out (about 120 days): start. This is when a new lender can hold a rate for you as a safety net, and when you can renew early with your current lender without a penalty.
Around 21 days out: the legal disclosure window. Your renewal statement must arrive by now, and the rate it shows cannot go up before your renewal date.
The maturity date: your old term has ended. You can renew, switch lenders, or pay down principal with no prepayment penalty.
If you do nothing: the lender usually auto-renews you, often at the posted rate, which is rarely the best deal you could have negotiated.
So when can I renew my mortgage, and when should I renew my mortgage? This is the mortgage renewal timeline that hangs off your mortgage maturity date. Start the conversation about four months before maturity, not the week the letter lands. A rate hold of up to 120 days works in your favour: if rates climb before you sign, you are protected, and if they fall, the lower rate can usually be captured for you. For a risk-averse Ottawa household worried about job stability, locking a safety-net rate early is often the calmest move. People also ask whether you can renew a mortgage early, and how early you can do it without a penalty. The answer is the same in each case: up to 120 days, no charge.
Want to model your new payment before we talk? Estimate it with the Ottawa mortgage calculator.
The part banks count on
The rate printed on your renewal letter is a starting point, not a final answer. Your existing lender has little reason to lead with its lowest pricing, because it is counting on something simple: most people sign and mail the slip back to avoid the hassle. Those who auto-renew leave money on the table. I have seen this from the inside. As I put it, the first mailed renewal offer is almost never the lender's best rate. Mortgage renewal rates move, and the rates Ontario lenders quote shift week to week, so it pays to compare across the field before you commit.
How to get a better rate
Do not sign first. Treat the mailed rate as the opening bid. Take it to the open market before you sign anything.
Bring a real alternative. A competing quote from another lender is what moves your current bank off its posted rate.
Ask plainly. Lenders hold internal discretionary rates they do not volunteer. Sometimes asking the right way, in writing, is enough.
Look past the headline rate. The Financial Consumer Agency of Canada advises comparing the term, prepayment privileges, portability, and fees, not just the number.
This is where my renewal coaching matters, even if you decide to stay. Knowing how to negotiate mortgage renewal terms is half the battle, and I will help you write the email to your existing lender with the wording that actually moves a rate, because a signature beats a full application when the lender can be persuaded. For live numbers, see today's best mortgage rates Ottawa context. No agent can promise you a perfect rate locked in advance, and you should be wary of anyone who claims one. What I can promise is that you will know the wider field before you sign.
Stay, switch, or renegotiate. We run the real numbers first.
Stay or switch
This is the question almost every renewing homeowner asks, and the honest answer is that switching is sometimes worth it and sometimes not. On the forums you hear both sides, from "no reason to stay with the same lender" to "it is not automatically better." Both are right, depending on your numbers. Here is the straight version.
The advantage is convenience: often just a signature, no re-qualifying, no appraisal, no legal fees.
You do not have to pass the stress test to renew with your current lender.
The downside is you will likely be offered a higher rate than you could negotiate or find elsewhere.
If you stay, do it with leverage, not loyalty: a competing quote in hand usually earns a better rate.
The benefit is competition: a new lender fighting for your business may offer a lower rate, plus cash-back or covered fees.
A "straight switch" (same balance, same amortization) means no penalty at maturity and no re-stress-test as of November 21, 2024.
The trade-off is paperwork: a new application, a new approval, and possibly some fees if the incoming lender does not cover them.
It is not always worth it. On a small balance, a 0.5% rate difference might save only a few hundred dollars a year, which may not justify the effort.
The right Ottawa example makes this concrete. A homeowner with a modest balance and a few years left was offered a slightly better rate just by asking the bank, then wondered whether chasing a switch for $615 a year in savings was worth it. Sometimes it is, sometimes a marginally higher rate with better prepayment flexibility wins. That is the math I run for you, for free, before you decide. The point is never to switch for switching's sake. It is to know the full cost of each option, then choose.
A common worry is whether anything can go wrong during a switch. For a straight switch the answer is reassuringly little. Your balance and amortization stay the same, you do not requalify under the stress test, and I manage the timeline so the file does not lapse between lenders. The horror stories you read, where a broker went quiet and a renewal lapsed, come from poor communication, not the switch itself. I am one WhatsApp message away, and I aim to be broker complete about three weeks before closing.
The 2024 rule change
This is the most important rule change for anyone renewing right now, and most homeowners do not know it. To renew with your current lender, you do not have to pass the mortgage renewal stress test. Renewing is an extension of your original contract, so as long as you change nothing, there is no requalifying. The bigger news is about switching. As of November 21, 2024, federal rules exempt both insured and uninsured borrowers from the stress test when they do a "straight switch" to a new federally regulated lender, under the Canadian Mortgage Charter. If you want the full picture of how the test works before and after this change, read my guide to the mortgage stress test in Canada.
To qualify for the straight-switch exemption
Your outstanding mortgage balance must stay the same.
Your amortization schedule must stay the same.
Both your old and new lenders must be federally regulated financial institutions.
If you want to borrow more or extend amortization, that is a refinance, not a straight switch, and the exemption does not apply.
Why does this matter so much in Ottawa? Because it removes the fear that once stopped people from shopping. If your income changed, if you are now self-employed, or if your credit took a knock, a straight switch lets you chase a better rate without being re-tested. It is one reason uninsured mortgage switches have climbed. If your situation has genuinely changed, through divorce or separation, a self-employment move, or bruised credit, I can map which lenders look at the whole picture rather than the label.
What it really costs
Here is the cost no Ottawa competitor lays out plainly, and the one most homeowners get wrong. Many confuse a renewal switch with buying a house and brace for a lawyer bill of three to five thousand dollars. For a straight switch at maturity, your real out-of-pocket cost is usually far smaller. These are dated examples for 2026 and vary by lender and file.
Switch costs, in dollars
Discharge fee: roughly $0 to $400, charged by your outgoing lender to remove its charge from your title. Federally regulated banks must disclose this in your original contract.
Appraisal fee: about $150 to $500, but a new lender often waives or covers it to win your business.
Legal / transfer fee: about $400 to $2,500, and on a straight switch the incoming lender frequently absorbs it.
Cash-back offsets: incoming lenders sometimes offer cash-back that can fully cover the transfer costs. Watch the fine print, because some cash-back is clawed back if you break early.
The hidden cost
The biggest number people fear, the prepayment penalty, usually does not apply at all if you wait for your maturity date, because your old term has ended. You can pay off or move the mortgage with no penalty then. If you break a mortgage before maturity, a fixed mortgage penalty is generally the greater of three months of interest or the interest rate differential (IRD), where the IRD reflects the gap between your rate and the lender's current rate for the time left, applied to your balance. Lenders often calculate the IRD using posted rather than discounted rates, which can make it surprisingly large. This is exactly why, as I say, a rate is not just a rate, the penalty matters. Two mortgages at the same rate are not equal once you count the cost to break one.
And the question on every homeowner's mind: does using a mortgage agent cost anything? No. You do not pay me a fee for arranging your renewal or switch. I am a licensed Mortgage Agent working under Referral Mortgages Inc., and shopping widely on your behalf is the work.
Renew or refinance
People mix these up constantly, so here is the clean distinction. A renewal is simply a new term on your existing balance and amortization. A refinance ends your current mortgage and starts a brand-new one, usually to change the structure. The difference decides your cost and your paperwork.
You just want a new rate and term
Your balance and amortization stay the same
You want to avoid heavy legal and appraisal costs
You are doing a straight switch with no penalty
You want to pull out home equity as cash
You want to consolidate high-interest debt
You want to extend your amortization to lower payments
You want to add a HELOC or change who is on title
For the 2020 to 2021 cohort facing a sharp jump, this distinction is the whole ballgame. Extending your amortization to lower the payment, for instance, requires a refinance, not a straight renewal. Choosing to refinance mortgage at renewal can be the right call when cash flow is genuinely tight, but it carries fees and converts flexible debt into debt secured against your home, so it is a conversation, not a default. If you think a refinance might fit, start with mortgage refinancing in Ottawa, then we will compare it against a plain renewal side by side.
If your payment jumped
If you are in the cohort renewing off a pandemic-low rate, a higher payment can feel like a wall. It is not. There are several honest levers, each with a trade-off, and the right one depends on your numbers.
Lump-sum at renewal: at maturity you can pay down as much principal as you like with no penalty, permanently shrinking the balance the new higher rate applies to.
Accelerated payments: switching to accelerated weekly or bi-weekly squeezes in the equivalent of one extra payment a year and chips down principal faster.
Extend the amortization: stretching the years lowers the monthly payment, but this needs a refinance and costs more interest over the life of the loan.
Consolidate debt: rolling high-interest balances into the mortgage can ease monthly cash flow, though it secures that debt against your home, so weigh it carefully.
Short-term deferral (last resort): some lenders allow a brief deferral, but unpaid interest is added to the balance, so it is breathing room, not forgiveness.
Aggressively shopping the renewal is the other lever, and for many it is the most effective. Because a straight switch no longer triggers the stress test, even a small rate discount can mean real savings over the term. I lay out which of these fit your situation and run the math before you commit to any of them.
Fixed or variable
This is the decision no Ottawa renewal page seems to address honestly, yet it is the one homeowners actually wrestle with. There is no universally right answer, only the right answer for your tolerance for uncertainty and your plans for the term. A fixed rate gives you a payment that will not move, which suits a risk-averse household, anyone worried about job stability, or a budget with no slack. A variable rate moves with the Bank of Canada and can cost less over time, but it asks you to absorb swings. If you might break the mortgage early, a variable typically carries a smaller, more predictable penalty, which ties back to the penalty-matters point above. We talk through where you sit, then look at current Ottawa rate context together.
A renewal handled, with someone in your corner.
Who you're working with
Mortgage in Ottawa is my practice as a licensed Mortgage Agent, arranging residential mortgages, renewals, refinances, and divorce or separation financing across Ottawa, Ontario.
I spent my early years in mortgages and banking at RBC and TD, then built my own practice 14 years ago on one principle: every client should feel like my only client. I am a solo practitioner, so the person you message is the person who knows exactly where your renewal stands. Each of the points below answers a real fear renewing homeowners told us about.
I will not go silent. The most common renewal horror story is a broker who stopped replying until the mortgage lapsed. No email sits longer than about 30 minutes in business hours, and during an active file you get a daily update. As I say, I am one WhatsApp message away.
I work for you, not the bank. Across my 2025 and 2026 funded files, business spread over 13 different lenders, banks, credit unions, and mortgage-only lenders, with more than 70% going somewhere other than the single biggest bank. That is shopping the field, not selling one shelf. It is a dated snapshot, not a promise.
I finish early. The goal is broker complete about three weeks before closing, so your final weeks are calm.
I am honest about cost. A rate is not just a rate, the penalty matters.
At a glance
Service area: Ottawa and the suburbs, Kanata, Barrhaven, Orleans, Nepean, and Stittsville, Ontario only, not Quebec or Gatineau.
Who it is for: homeowners with a mortgage coming up for renewal, deciding whether to stay or switch.
Response: one WhatsApp message away, replies within about 30 minutes in business hours.
Cost to you: none.
Credential: Mortgage Agent Level 1 with Referral Mortgages Inc., FSRA brokerage licence #13316
Next step: Apply Now, book a renewal review, or WhatsApp 613-294-4475.
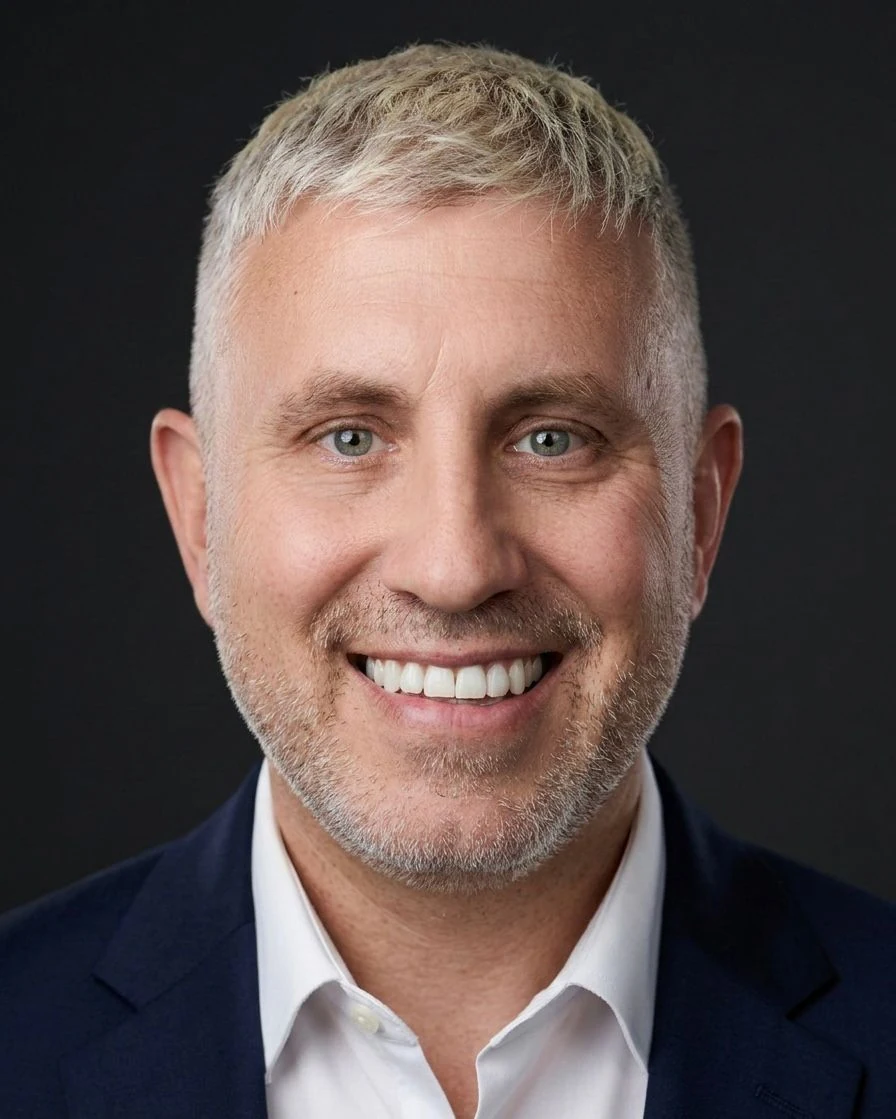
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316
More ways I can help
One agent for the whole picture. Whatever stage you are at, here is where to go next.
4.9 stars from 64 Google reviews left by clients I have worked with across Ottawa.
Mortgage in Ottawa · Nick Bachusky, Mortgage Agent · 1320 Carling Avenue, Suite 205, Ottawa, ON K1Z 7K8 · 613-294-4475 · nick@mortgageinottawa.com
Get in touch
Getting a mortgage does not need to be stressful. Leave your details and I reply within about 30 minutes during business hours.
Still wondering?
Both can be right. Staying is convenient and means no re-qualifying, but your bank rarely leads with its best rate. Switching can win a lower rate plus cash-back, especially as a straight switch with no penalty at maturity. The deciding factor is the full cost of each option, not the headline rate. I run that comparison for you before you choose.
Sometimes yes, sometimes no. On a large balance, even a small rate drop saves real money, so switching often pays. On a small balance, a 0.5% difference might save only a few hundred dollars a year, which may not justify the paperwork. The honest move is to weigh the saving against the effort and any fees. We do that math together so the answer is based on your numbers.
No, not to renew with your current lender. Renewing is an extension of your existing contract, so as long as you change nothing, there is no requalifying. For switching, as of November 21, 2024, federal rules exempt borrowers from the stress test on a straight switch to a new federally regulated lender, provided your balance and amortization stay the same. That change makes shopping your renewal far easier than it used to be.
If you do nothing by your maturity date, your lender usually auto-renews you, often at its posted rate, which is rarely the best deal. If a broker fails to file paperwork in time, the mortgage can temporarily lapse and create stressful complications. The fix is simple: start about four months early and keep someone responsive on the file. I manage the timeline so nothing slips through the deadline.
With your current lender you can usually renew early up to 120 days, about four months, before your maturity date with no prepayment penalty. A new lender can also hold a rate for you for up to 120 days as a safety net. So starting four months out costs you nothing and protects you if rates rise. If they fall before you sign, the lower rate can often be captured for you instead.
What documents are required for mortgage renewal depends on your path. If you simply accept a straight renewal with your current lender, you usually just sign and return the letter, no new paperwork. If you switch lenders or refinance, you submit a new application. Expect to provide government-issued ID, income proof such as recent pay stubs and a T4, a recent property tax bill, proof of property insurance, and a void cheque to set up payments.
No. Renewing is a new term on your existing balance and amortization, with little or no cost on a straight switch. Refinancing ends your current mortgage and starts a new one, usually to pull out equity, consolidate debt, or extend amortization, and it carries legal and appraisal fees. A straight switch to a new lender at renewal is still a renewal, not a refinance, as long as the balance and amortization do not change.
Renewing with your current lender is typically free. On a straight switch your only real out-of-pocket cost is usually the discharge fee, roughly $0 to $400, and the incoming lender often covers appraisal and legal fees or offers cash-back.
Do not sign the mailed offer first, treat it as the opening bid. Bring a real competing quote from another lender, because that is what moves your bank off its posted rate. Ask plainly and in writing, since lenders hold discretionary rates they do not volunteer. I coach the exact email wording that earns a better rate, even if you ultimately decide to stay with your current lender.
Yes, in part. You have never needed the stress test to renew with your current lender. The new piece is that, as of November 21, 2024, both insured and uninsured borrowers are exempt from the stress test when doing a straight switch to a new federally regulated lender, under the Canadian Mortgage Charter. The condition is that your balance and amortization stay the same. Borrow more or extend amortization and it becomes a refinance.
At your maturity date your term ends but the remaining balance does not. You sign a new term, either with your current lender or a new one, and at that moment you can renew, switch, or pay down principal with no penalty. Your lender must send you a renewal statement at least 21 days before the term ends. Doing nothing usually triggers an auto-renewal at a less favourable posted rate.
Often yes. Because a straight switch to a new federally regulated lender no longer requires passing the stress test, a changed situation does not automatically lock you in with your current bank. If your circumstances shifted through separation, a move to self-employment, or a credit setback, the right lender matters. I map which lenders weigh the whole picture rather than a single label, so you still have options.
It depends on your tolerance for uncertainty and your plans for the term. A fixed rate keeps your payment steady, which suits a risk-averse budget or anyone worried about job stability. A variable rate moves with the Bank of Canada, can cost less over time, and usually carries a smaller penalty if you break early, but it asks you to absorb swings. There is no single right answer, so we match it to your situation.
No pressure, no rush. Whether your mortgage is months from maturity or the letter just arrived, the earlier we start, the more leverage you have.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316. There is no cost to the client on standard residential mortgages. All rate, penalty, fee, and dollar figures on this page are accurate as of June 2026 and are dated examples, not guarantees.