S
Sharon
Google reviewGreat guy! Nick was the most helpful in my first home buying experience. Very reliable and personable. Highly recommend.
Read Google reviews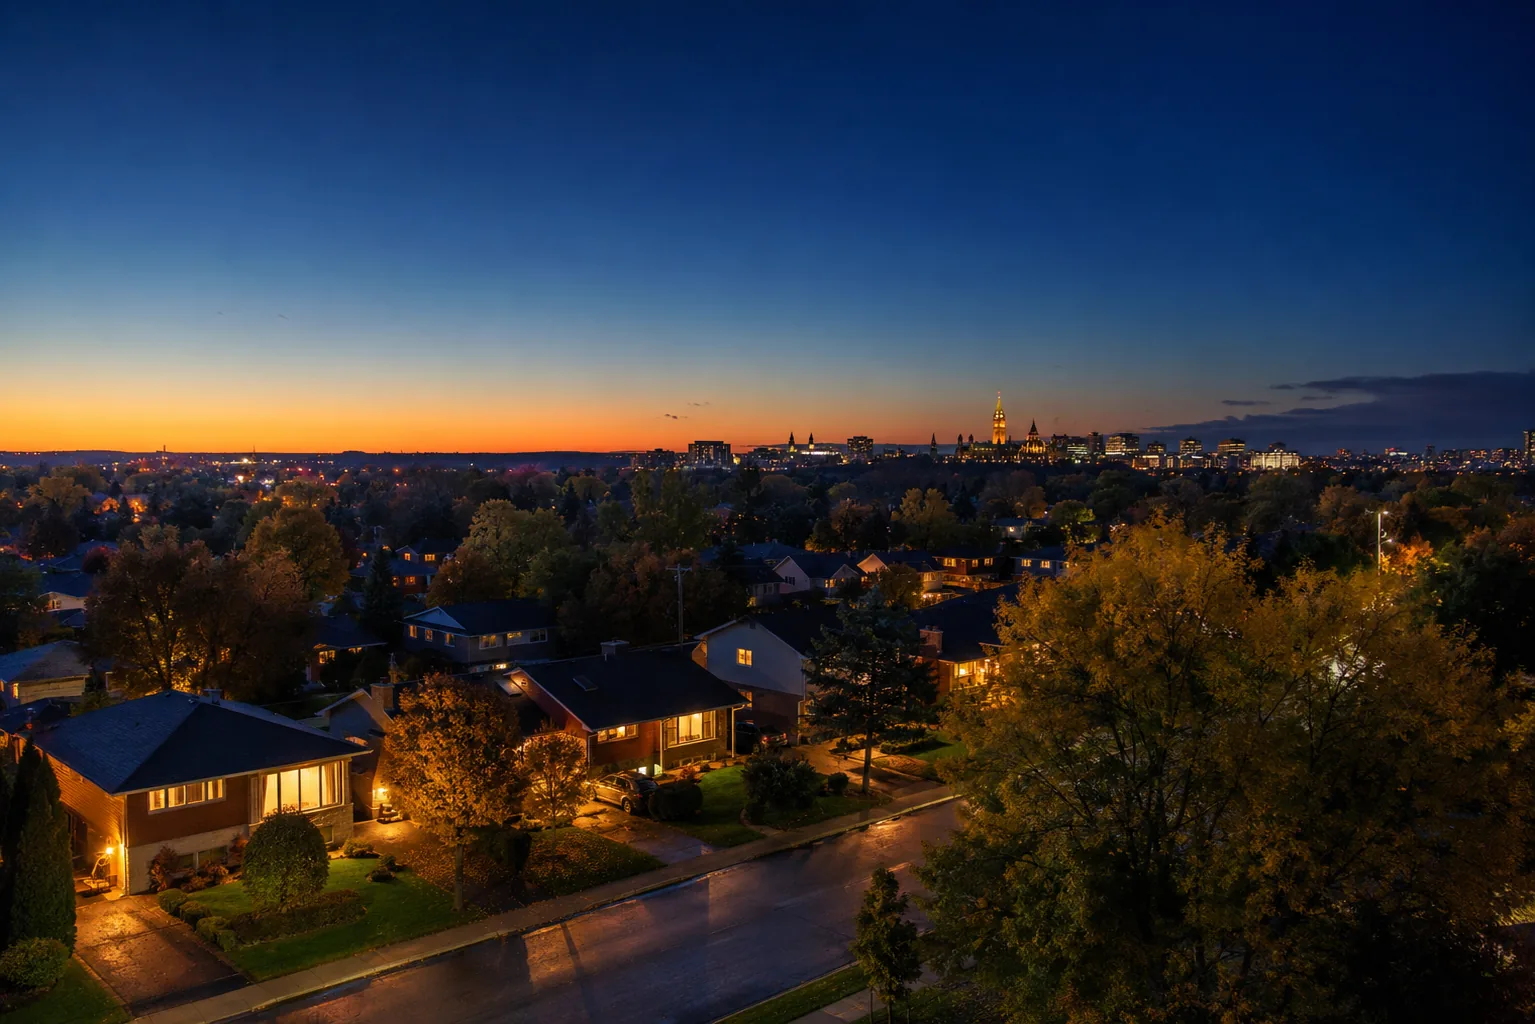
Nepean · West Ottawa
A local mortgage agent for Nepean buyers, renewers and refinancers, across older bungalows, newer infill builds and condos. I work for you, not a bank.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316 · 14 years · serving Nepean and west Ottawa.
The short answer
I am a licensed Mortgage Agent working across Nepean and west Ottawa (Level 1, Referral Mortgages Inc., FSRA brokerage licence #13316). I arrange first home purchases, renewals, refinances and mortgages during a separation. Only I touch your file, from the first call to the day it funds, and I am one WhatsApp message away.
Who it's for
Once your file is open, most of it moves by phone, email and a secure portal, so being nearby does not on its own get you a better rate. What matters is what fourteen years here taught me about this market, after my years at RBC and then TD. That is also why I left the bank and how I work now.
First-time buyers getting their first pre-approval, often on a condo townhouse in Tanglewood or a bungalow off Merivale Road. first-time home buyer mortgages in Ottawa.
Owners renewing who want a second opinion before they sign the letter their bank mailed out. your mortgage renewal options.
Owners refinancing to consolidate debt or fund a renovation on a home built in the 1960s. refinancing to consolidate debt or free up equity.
Couples separating who need to sort out what happens to the house, calmly and privately. mortgage help during separation or divorce.
Condo and townhouse owners where the status certificate and the reserve fund decide as much as the rate does. condo mortgages in Ottawa.
Move-up buyers outgrowing a starter home and carrying two conversations at once, selling one property while financing the next.
Self-employed and tech-paid buyers because steady federal T4 pay and tech pay carrying RSUs and bonuses need very different documentation before a lender will count them.
For a real answer rather than a guess I need six things: your situation, your goal, your timing, your income, your down payment and your budget. Send those to me with your application, or bring them to a booked call, and I can tell you where you actually stand. If you want to sanity-check a payment first, the Ottawa mortgage payment calculator will get you close.
"Every client should feel like my only client." Nick Bachusky
On the ground here
Nepean is not one market, it is a dozen small ones, and knowing the difference shapes how I put your file together. Most homes here were built between 1950 and 1980, so I flag ageing furnaces and wiring early.
Bells Corners. The western edge against the Greenbelt, with Lynwood Village at its core, roughly 1,700 homes from the 1950s and early 60s. 126 sales averaged $522,857. An appraisal here usually turns on what has been updated since.
Centrepointe. A 1985 Minto master-planned community around Ben Franklin Place, averaging $632,633. Only about 40 percent of it is detached, so many files here are terrace condos needing a status certificate and a reserve fund review.
Arlington Woods and Craig Henry. Arlington Woods posted Nepean’s strongest appreciation, averaging $801,529. Craig Henry took a direct hit from the 2018 EF-2 tornado, and the rebuilds it set off are still visible today.
Meadowlands and Manordale. Detached homes run from $610,000 to over $1.05 million while condo townhomes start near $300,000, which puts two buyers on the same street in completely different down payment tiers.
Parkwood Hills and Fisher Heights. Steady older stock, heavy on apartment condos that are under downward pricing pressure right now, so I leave extra time for the condo documents on a file here.
Copeland Park and City View. Mid-century homes on deep lots, some bought for the land and rebuilt. A teardown rebuild is underwritten as construction financing rather than as a plain resale purchase.
Price varies block by block. The average sale across all home types in Nepean sat at $625,000 for the year ending June 2026, up 4.0 percent, against an Ottawa wide average of $733,648 (OREB). Two pockets sit well above that: Qualicum averaged $935,852, and Crystal Beach, beside Andrew Haydon Park on the Ottawa River, averaged $920,726. At those prices you move into a larger CMHC down payment tier, so it is worth knowing what a pre-approval will actually support before you start looking.
Every mortgage is also qualified at the greater of your contract rate plus 2 percent, or 5.25 percent, a stress test in place since June 2021 (OSFI). Budget past the down payment too, for Ontario land transfer tax, the first-time buyer refund of up to $4,000, legal fees and an inspection. There is no municipal land transfer tax in Ottawa, unlike Toronto. You can run the numbers on a Nepean price band before we talk.
Near Qualicum, the Queensway Carleton Hospital keeps demand steady, and Algonquin College does the same for Centrepointe and Craig Henry. Baseline Station's O-Train expansion is targeted for late 2027, which shapes how I would time a purchase nearby. (I am a licensed Mortgage Agent working under Referral Mortgages Inc.)
Every client should feel like my only client.
What I arrange
This is the short version. Each service has its own full page for Ottawa. The same help applies right here in Nepean.
Get pre-approved, understand your real budget, and use the programs you qualify for.
first-time home buyer mortgages in OttawaKnow what a lender will actually support before you start shopping.
getting pre-approved for a purchaseDo not sign the first renewal letter. Decide with leverage, not loyalty.
renewing a mortgage in OttawaFree up equity or roll high-interest debt into one lower payment.
refinancing to consolidate debt or free up equityKeep the home where it makes sense, with a calm one-income plan.
mortgage help during separation or divorceNepean has a deep condo and stacked-town market, so the due diligence matters.
condo mortgages in OttawaCompare options across banks, credit unions and monoline lenders.
today's Ottawa mortgage ratesAgent vs bank
A bank branch can only offer what that bank has on its shelf that week. I take one application to several lenders instead. That is the core difference, and in Ontario it is set by the rules, not by opinion.
Most people use the two titles interchangeably, and for what you actually need the difference does not change much. I am a licensed Mortgage Agent working under Referral Mortgages Inc., not a broker, but I do exactly what people picture: shop the whole market for you.
On an older Nepean home that breadth matters more than usual, because lenders set their own guidelines on original wiring, knob and tube, and aluminium. The shelf you land on can decide whether your file sails through or stalls.
I also choose on total cost, not the headline rate. A rate is not just a rate. The penalty to break the mortgage is the hidden cost, and when two lenders match on rate I lean toward the one with the smaller penalty, because life happens and rates can fall. That is why I look at why the penalty can matter more than the rate before I look at the headline number.
Shopping your file to too many lenders in a short window can mark your credit, so ask how many lenders your file will actually go to before you say yes to anyone. And mortgages are private, so I do not publish client names or stories. What I can show you instead is my licence, my reviews, and exactly how I would handle your situation.
"A rate is not just a rate, the penalty matters." Nick Bachusky
Broker complete about three weeks before closing, so you are focused on the house.
Why trust Nick
Your mortgage is one of the biggest financial commitments you will make, so it matters who is on the other side of the file. As I put it, I am one WhatsApp message away.
14 years
in mortgages
Arranging mortgages after years at RBC and TD. My office is at 1320 Carling Avenue, Suite 205, a short drive up the road from most of Nepean.
FSRA brokerage licence #13316
licensed in Ontario
Mortgage Agent Level 1 under Referral Mortgages Inc. You can verify the licence on the FSRA public register.
13 lenders
across 38 funded files
Between 2025 and 2026, with more than 70 percent placed away from the single biggest bank on that list. A dated snapshot of funded files, not a promise about your result.
Only me
on your file
From the first call to the day it funds, with no handover to a processing team partway through. You get daily updates while your file is underwritten, not silence until something goes wrong.
4.9 stars from 64 Google reviews left by clients I have worked with across Ottawa.
Get in touch
Getting a mortgage does not need to be stressful. Leave your details and I reply within about 30 minutes during business hours.
Nepean mortgage FAQ
The real downside is access, not honesty. Not every lender works with agents, so if you want one bank’s exclusive product, a branch is the more direct path. Checking your file with too many lenders in a short window can also show up on your credit report. Ask any agent how many lenders they actually approached.
You do not pay me a fee for a standard residential mortgage. My compensation comes from the lender once your file funds, which is how most brokerages work under Ontario’s FSRA licensing rules. If a borrower with good credit is asked for a fee of 1 percent on a straightforward A lender mortgage, question it before signing.
Not always, and that is normal. A mortgage agent takes one application to several lenders instead of offering one bank’s products, so you compare real options rather than a single number. Whether it ends up cheaper depends on your file and on what lenders are offering that week, but more options usually work in your favour.
Ask before you commit, because from the outside everyone looks competent. What is the penalty if I break this mortgage early, and how is it calculated. Which lenders did you actually approach for my file, and why this one. Will you charge me a fee, and in what situation. What is your licence number, and who is your brokerage. Who will I talk to if something goes wrong partway through, and how will you keep me updated while my file is underwritten. Someone who has read your file, explains plainly how they are paid, and answers straight about their licence is doing the basic job right, whoever you choose.
In Ontario the FSRA licence levels are Agent and Broker. An agent must work under a licensed brokerage, while a broker can supervise other agents. I am a Mortgage Agent Level 1 with Referral Mortgages Inc., FSRA brokerage licence #13316, and I arrange mortgages within that regulated framework.
Ontario’s regulator, FSRA (the Financial Services Regulatory Authority of Ontario), keeps a public record of every licensed mortgage agent and broker in the province. My licence number is #13316, held as a Mortgage Agent Level 1 under Referral Mortgages Inc. Read FSRA’s guidance on working with a mortgage professional
I work across Nepean, including Bells Corners, Centrepointe, Craig Henry, Arlington Woods, City View, Manordale, Meadowlands, Qualicum, Crystal Beach, Parkwood Hills, Tanglewood, Knoxdale, Fisher Heights and Copeland Park. If your street is not on that list, it is still very likely inside the area I cover. Send me a message and I will confirm.
As of November 2024, OSFI does not expect lenders to reapply the stress test to a borrower who is simply renewing with the same lender. Switching to a new lender still needs that lender’s approval and legal registration of the new mortgage, so it is not automatic, but the stress test is no longer the obstacle it once was (FCAC).
Other Ottawa areas
I serve the whole city. Explore my other Ottawa-area pages, or browse all my Ottawa mortgage services.
Get started
No pressure, just quick honest answers. Start your application or book a time, and I will tell you honestly where you stand. Every file comes to me directly, not to an assistant or a call centre.
Nick Bachusky · Mortgage Agent Level 1 · Referral Mortgages Inc. · FSRA brokerage licence #13316. Rate, penalty and price figures are dated examples for 2026, grounded in CMHC, OSFI, FCAC, OREB, Ontario.ca and City of Ottawa sources, and are not guarantees.